Proposed purchase priceSELLER
$13.0mTransaction room active
STRATEGIC ACQUISITION & PARTNERSHIP OPPORTUNITY
A landmark asset.
A measurable recovery.
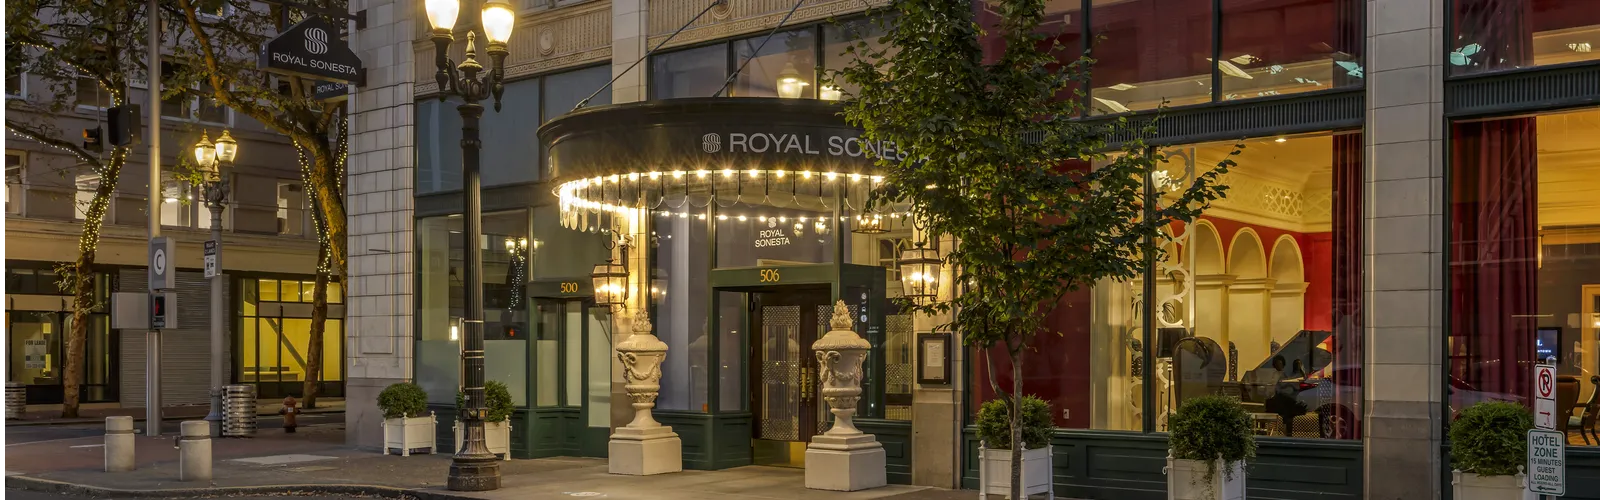
506 SW Washington Street • Downtown Portland, OregonSELLER-PROVIDED$13m proposed acquisitionwith brand-supported seller financing
THE TRANSACTION AT A GLANCE
A clean path to transfer the asset — and preserve long-term upside
MyntGroup proposes a ring-fenced transaction designed to recapitalize the property, preserve the Royal Sonesta identity and restore competitive performance.Seller financingSELLER
$7.0mGuest rooms / keysVERIFIED
221Price per keyCALCULATED
$58,824Gross building areaPUBLIC DATA
≈18,580 m²2016 acquisition priceVERIFIED
$114.0mEvidence disciplineVERIFIED independently sourcedSELLER-PROVIDED supplied transaction informationPROPOSED Mynt structure under discussionILLUSTRATIVE calculated scenario
01 — THE ASSET
Substantial scale in the heart of downtown Portland
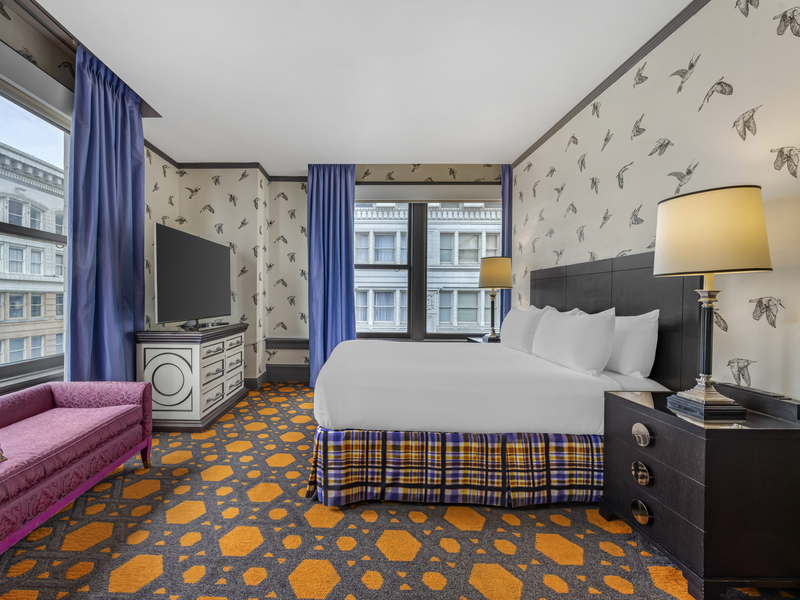
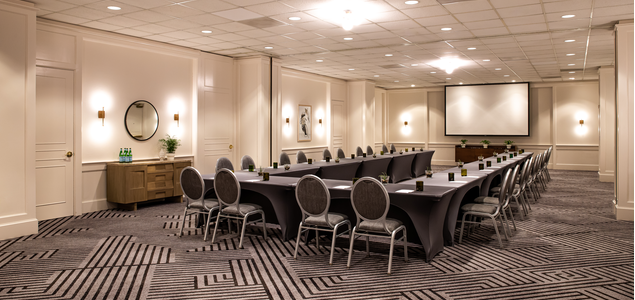
The property combines an unusually high suite mix with meeting space, food and beverage operations and an established upper-upscale brand identity.
221keys
135suites
10–11floors
1912building origin
2020corridor & meeting renovation
02 — STAR PERFORMANCE
The market is operating.
The property is not capturing its fair share.
STR’s October 2025 report shows a property-specific performance gap versus five direct competitors. Competitive-set data excludes the subject property.
2025 YEAR TO DATESTAR REPORT
MARKET POSITION
6th of 6on occupancy and RevPAR$2.87millustrative annual room-revenue gap at comp-set RevPARBased on 221 keys × 365 nights. Not a forecast.
Direct competitive setHotel LuciaKimpton Hotel VintageHeathman HotelThe ParamountDossier Hotel
03 — FINANCIAL SNAPSHOT
Revenue is growing modestly while the operating loss deepens
The snapshot supplied for the transaction indicates that higher revenue does not currently translate into improved EBITDA. Detailed departmental P&Ls, fixed charges and NOI remain due diligence items.
USD2024 T-122025 BudgetChange
Total revenue$4,482,910$4,685,175+$202,265 / +4.5%
Rooms revenue$3,139,664$3,352,503+$212,839 / +6.8%
Implied operating cost$6,693,820$7,310,954+$617,134 / +9.2%
EBITDA($2,210,910)($2,625,779)($414,869) worse
EBITDA margin−49.3%2024 T-12
EBITDA margin−56.0%2025 budget
NOIPendingfixed charges and ownership costs required
04 — INDICATIVE TURNAROUND PLAN
The opportunity is operational recovery—not financial engineering alone
The current performance gap requires a funded, hands-on stabilization plan. The actions below are a proposed operating framework and will be refined after access to departmental results, contracts, staffing data and property-condition reports.
Protect liquidity
Install weekly cash controls, approve a protected working-capital reserve and review every major contract, department and staffing schedule.
Recover revenue
Reset pricing, distribution and sales activity; rebuild corporate, group and meeting demand; and improve direct-channel conversion.
Close the gap
Target disciplined occupancy and RevPAR recovery toward the competitive set while improving suite, meeting-space and food-and-beverage contribution.
Stabilize and refinance
Build an auditable operating record, address the seller-note maturity and position the property for long-term capital or portfolio integration.
ILLUSTRATIVE • NOT A FORECAST$2.87mannual room-revenue gap at 2025 comp-set RevPAR
This gap illustrates why Portland may support a turnaround thesis, but it does not represent EBITDA, NOI or guaranteed upside. Conversion depends on operating costs, renovation needs, market conditions and execution.
05 — INDICATIVE CAPITAL STRUCTURE
Brand-supported financing creates a credible starting point
The terms below are discussion terms supplied for this opportunity and remain subject to capital commitments, diligence, approvals and definitive documentation.
$13mpurchase price
$7m seller financing$6m closing capital
Seller financing$7.0m
Interest rate6.0–6.5%
AmortizationInterest-only
Initial term24 months
Annual cash interest$420k–$455k
Closing capital$6.0m to be arranged
CAPITAL SOURCING PATHWAY
$6m from third-party investors
MyntGroup intends to arrange the remaining closing capital from external investors rather than funding the equity cheque from its own balance sheet.
≈2,500MyntGroup shareholders and a wider investor network provide an established audience through which the opportunity may be introduced.
Access to an investor and shareholder network is not a funding commitment. Capital remains subject to investor diligence, securities-law compliance, approvals and definitive subscription documentation.06 — ZERO-CASH-TO-MYNT CONCEPT
Mynt can sponsor and control the transaction without funding the equity cheque itself
This is a proposed structure—not committed financing. The central concept is to separate ownership control, investor economics and hotel-level risk within a dedicated SPV.
01Sonesta / seller$7m secured seller note6–6.5% • interest-only • 24 months
+02Third-party capital$6m closing equityplus a separately funded turnaround reserve
→03Mynt-controlled SPV$0 Mynt cash at closingsponsor equity • governance • buyout rights
ILLUSTRATIVE
$4m–$6m turnaround reservePotential additional investor capital to protect operations during stabilization. Final need depends on diligence and the approved business plan.
Ring-fenced property entityNo personal guarantee proposedInvestor preferred returnMynt performance promoteExtension / refinance rights
07 — STAKEHOLDER ALIGNMENT
One transaction. Four aligned outcomes.
The structure should solve the seller’s current problem while preserving the brand relationship, protecting new capital and giving Mynt a repeatable acquisition platform.
Service Properties Trust
A documented path to transfer the asset and remove ongoing operating exposure.
Sonesta
Brand continuity, lender economics and a recapitalized property.
Capital partner
Preferred economics, asset-level security and defined governance rights.
MyntGroup
Sponsor ownership, operational oversight and a foundation for future deals.
Outright acquisitionDefined sale with seller financing and brand continuity.
Strategic rolloverSeller retains debt or preferred participation in the recovery.
Portfolio relationshipPortland becomes the first transaction in a repeatable framework.
08 — STRATEGIC PARTNERSHIP & ROLL-UP
Portland as the cornerstone of two scalable hospitality platforms
Rather than treating Portland as a standalone disposal, MyntGroup proposes inviting the seller to participate as a strategic founding partner in a broader real-estate and hotel-operating platform.
Hotel Real Estate Platform
$1.5bn–$3.0bnTarget gross real-estate asset value assembled through acquisitions, seller financing, asset contributions and institutional capital.
- Owns ring-fenced hotel properties
- Receives rent or property-level income
- Creates an institutional real-estate portfolio
SEPARATEownership+operations
Hotel Operating Platform
$500m–$700mTarget enterprise value for a scalable hotel operator built across an initial portfolio of approximately 10–15 hotels.
- Operates hotels and brand relationships
- Centralizes revenue management and procurement
- Scales fee income and operating performance
THE SELLER'S LONG-TERM UPSIDE
Potential participation beyond the sale
In addition to the proposed $7m interest-bearing seller note, the seller may receive strategic founding participation in both platforms—aligning the seller with the wider roll-up rather than limiting its economics to Portland alone.UP TO10%in PropertyCo
UP TO10%in HotelCo
01Acquire & stabilizeComplete Portland, protect liquidity and restore operating performance.
02Build the portfolioTarget 10–15 hotel transactions using repeatable capital structures.
03InstitutionalizeAudited reporting, independent governance and scalable management.
04Public-market pathwayPursue separate listings in approximately 24 months, subject to readiness.
The portfolio sizes, valuations, ownership percentages, transaction count and approximately 24-month listing objective are strategic targets only. They are not forecasts, guarantees, committed financing or offers of securities. Any participation would be fully diluted, subject to future financing dilution, and documented only through definitive agreements.
09 — DEAL DOCUMENTS
The evidence behind the proposal
Documents are separated from the main MyntGroup DataRoom and relate only to the Portland opportunity.
VERIFIED SOURCE
Download ↓Monthly STAR Report — October 2025
Occupancy, ADR, RevPAR, segmentation, ranking and competitive-set performance.
MYNT PROPOSAL
Download ↓Strategic Acquisition & Partnership Proposal
12-slide seller- and brand-facing transaction presentation.
Next documents requested from seller
01Fee-simple title, liens and property tax records
02Detailed monthly P&L, fixed charges and NOI bridge
03Sonesta management / brand agreements
04PIP, engineering and deferred-maintenance reports
05FF&E inventory and capital expenditure history
06Draft seller-financing term sheet and security package